[Get the free guide] [Calculate your real cash requirement]
We are licensed real estate brokers, not mortgage advisers. This page explains what the rules are and what the arithmetic implies. It names no bank, no lender and no product, and it recommends none. Eligibility varies by lender and anything you plan to rely on should come from a lender or a regulated mortgage adviser.
Trust bar
| 50% | 56.6% | 2% |
|---|---|---|
| Universal CBUAE off-plan LTV cap, all buyer categories | Real liquid capital needed on an AED 2m unit at that cap | Abu Dhabi registration fee, per the government's own portal. Dubai is 4% |
The LTV matrix
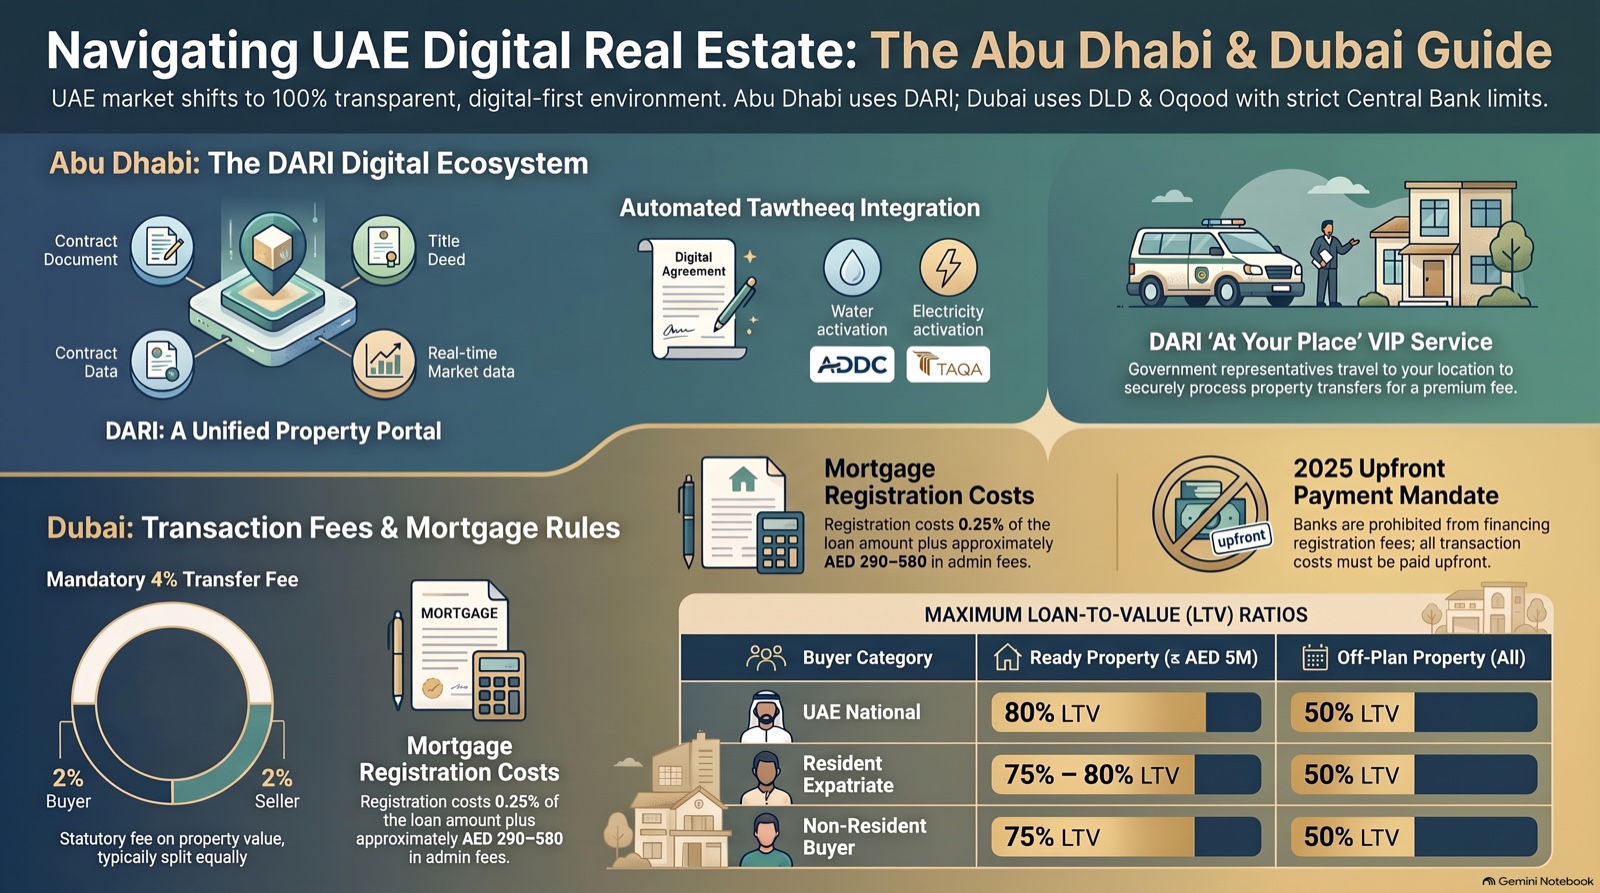
| Buyer category | Ready property | Off-plan property |
|---|---|---|
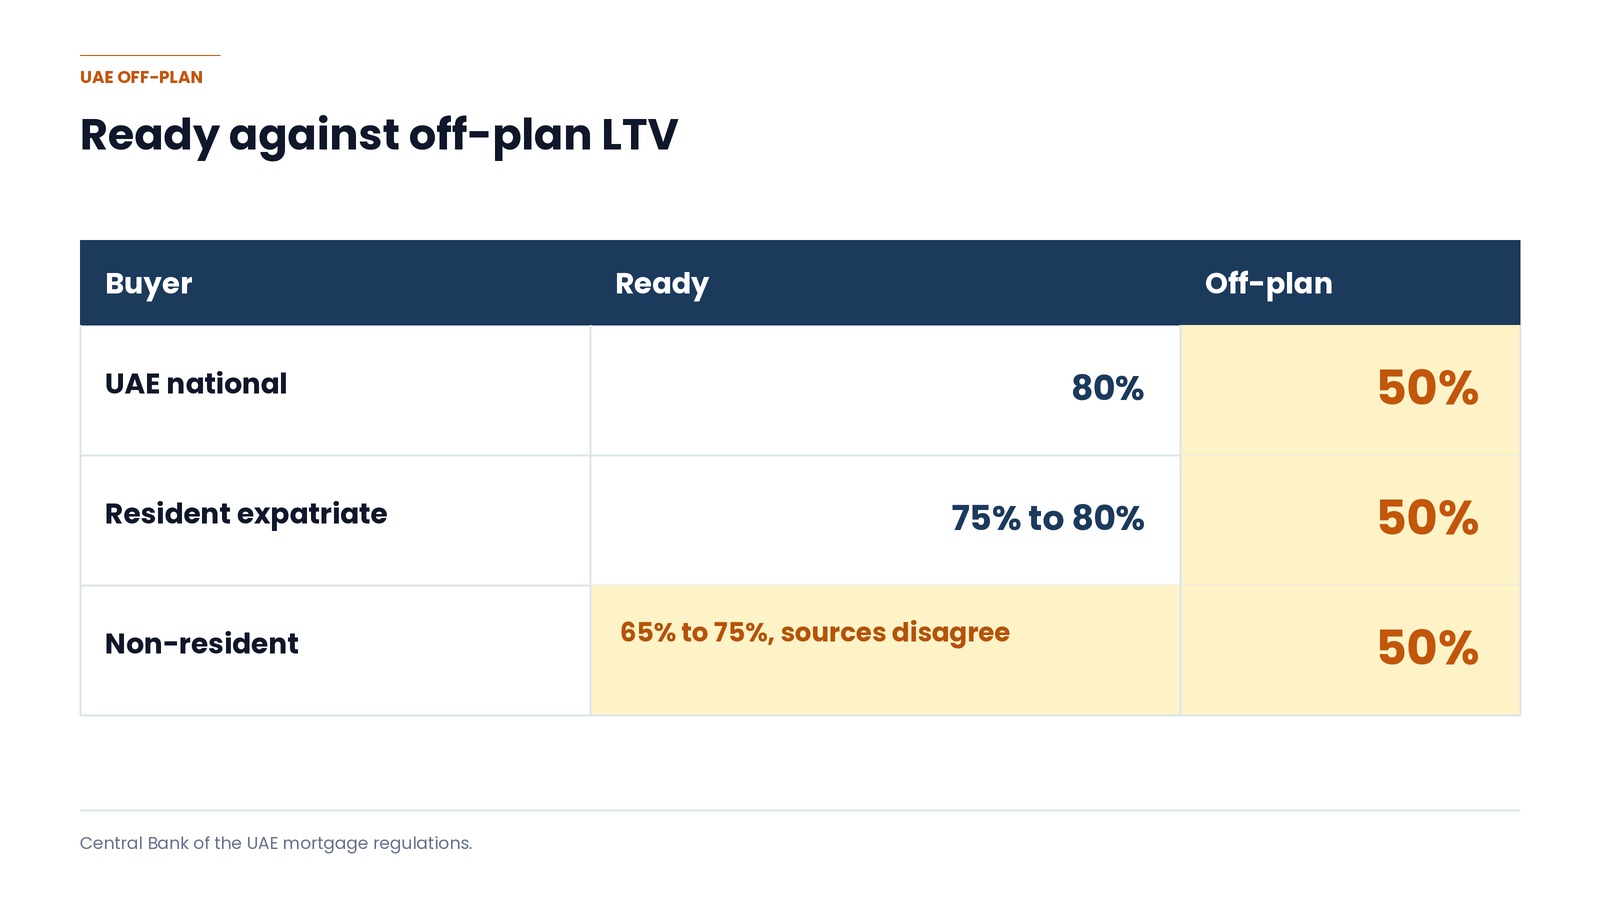
| UAE national | 80% | 50% |
| Resident expatriate | 75% to 80%, and 60% on a second home | 50% |
| Non-resident | 65% to 75%, sources disagree | 50% |
The off-plan column does not move. The Central Bank's cap is universal and applies regardless of nationality or residency.
Two qualifications, stated rather than smoothed over. One source quotes the ready figures at or below AED 5 million and the others state no threshold. And the non-resident ready figure is 65% in one lender-side source and 75% in two others, which is too wide a spread to publish as a single number.
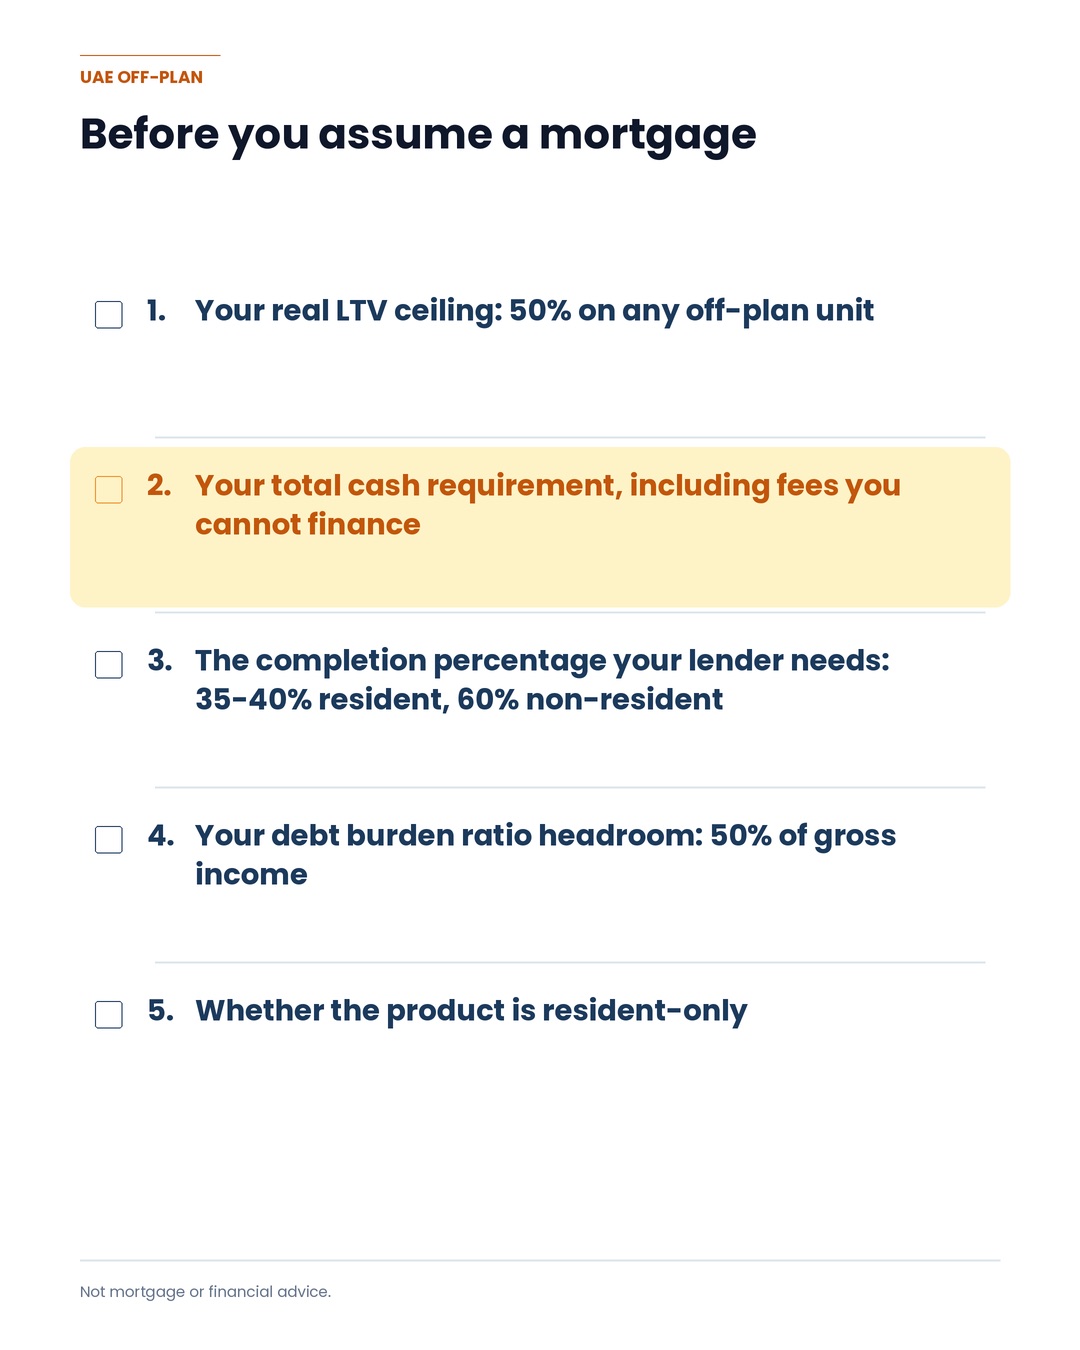
The practical consequence: if you are buying off-plan and modelling an 80% mortgage, you are modelling a product you cannot have. That is the most common financing error we see.
[INLINE CTA #1]
Fifty-Seven. A 26-page guide to what a UAE bank will lend on an off-plan unit and what it costs in cash, with a printable cash-requirement worksheet. No bank named, nothing recommended.
[Download free]
50% LTV is not 50% cash
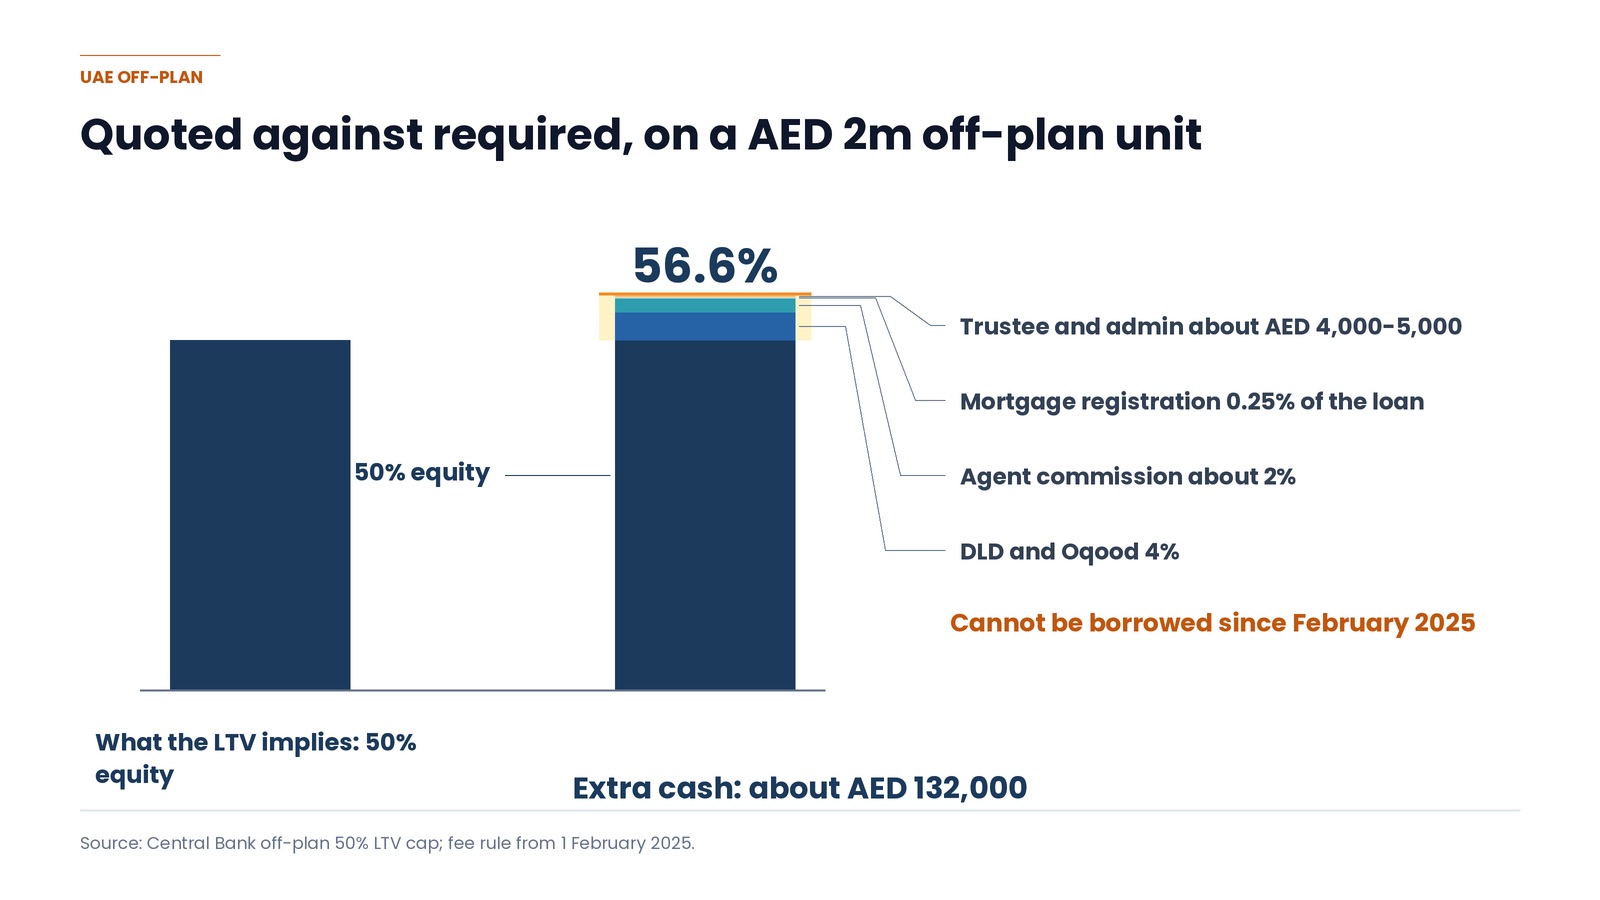
From 1 February 2025, banks are prohibited from financing transaction fees. Land department registration and broker commission come out of pocket, in cash, and cannot be rolled into the loan.
| Fee | Amount |
|---|---|
| DLD transfer and Oqood registration | 4% of property value |
| Agent commission | typically 2% of property value |
| Mortgage registration | 0.25% of the loan |
| Trustee and admin | approximately AED 4,000 to AED 5,000 |
Worked on an AED 2,000,000 off-plan unit at 50% LTV:
| Line | Amount |
|---|---|
| Mortgage | AED 1,000,000 |
| Equity contribution | AED 1,000,000 |
| Fees, unfinanceable | approximately AED 132,000 |
| Total liquid capital required | approximately AED 1,132,000, or 56.6% of price |
Roughly seven percentage points above the headline LTV, and it has to be cash sitting in an account rather than in a loan.
Approval is not disbursement
A bank can approve an off-plan mortgage. That is not the same as the money arriving.
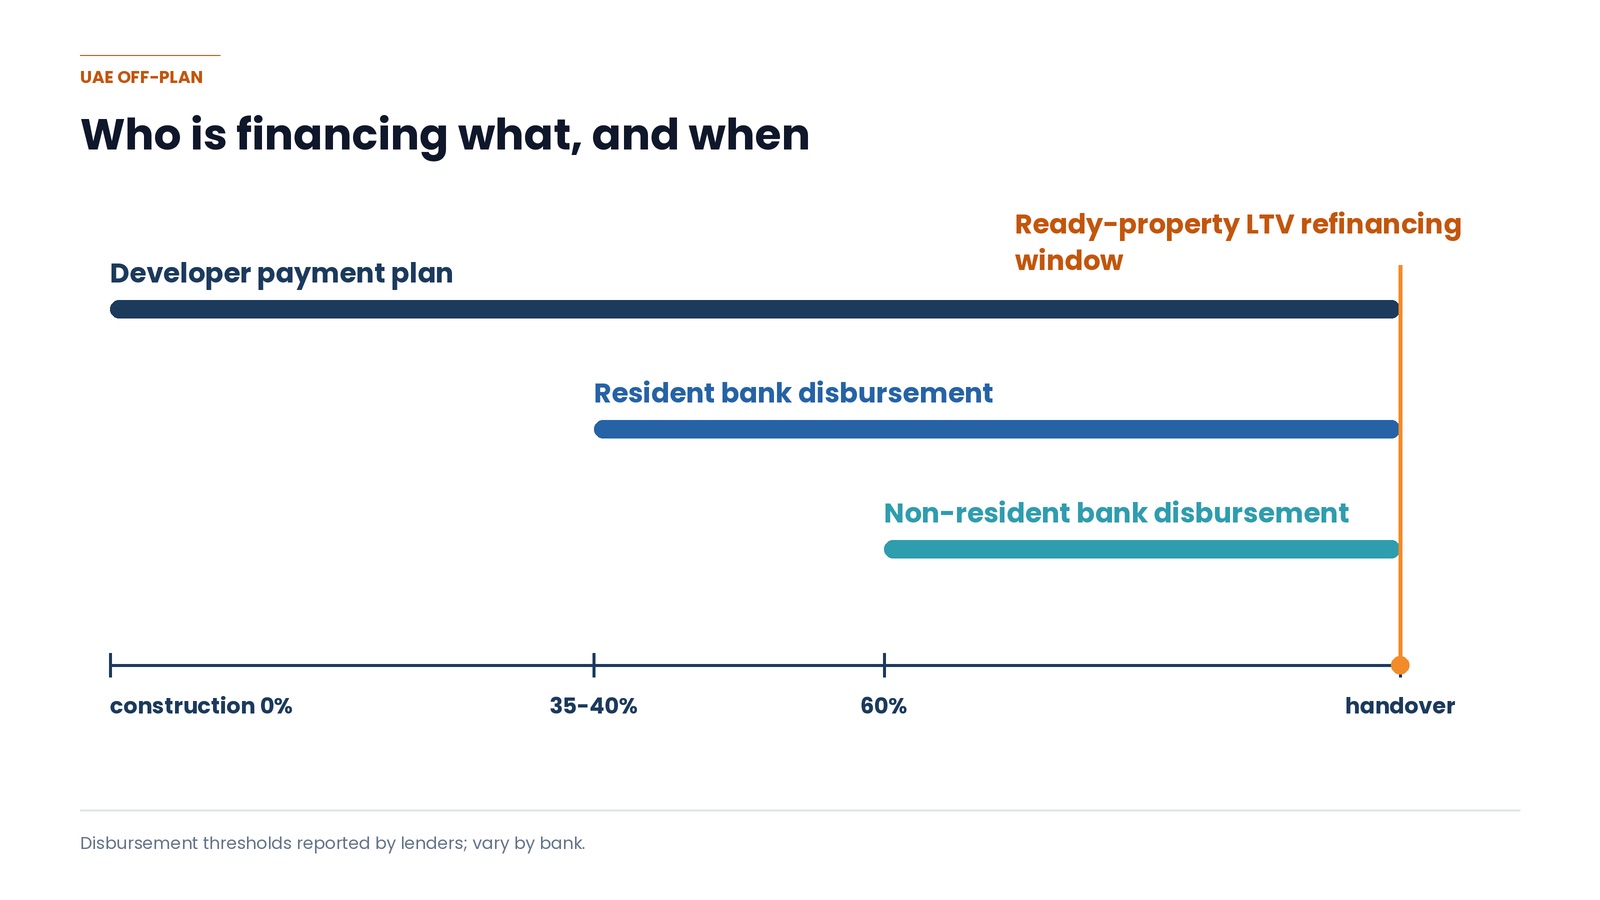
Lenders tie disbursement to construction progress, because until the building exists there is no completed asset securing the loan.
| Borrower | Typical disbursement threshold |
|---|---|
| Resident | 35% to 40% construction complete |
| Non-resident | 60% construction complete |
Which is the structural point of this page: for the first third to two-thirds of construction, the developer's instalment plan is your financing, whether or not you chose it as your financing. The bank is not an alternative to a developer plan early on. It is a later stage of the same journey.
If you are choosing a payment plan on the assumption that you will refinance out of it early, the disbursement rules do not permit that.
[INLINE CTA #2]
Calculate your real cash requirement. Send us the unit price, your buyer category and whether it is off-plan or ready. We will return your LTV ceiling, your equity contribution, every unfinanceable fee itemised, and the total as a percentage of price.
Property service, not mortgage advice. We do not quote rates, recommend lenders or arrange finance.
[Run the numbers]
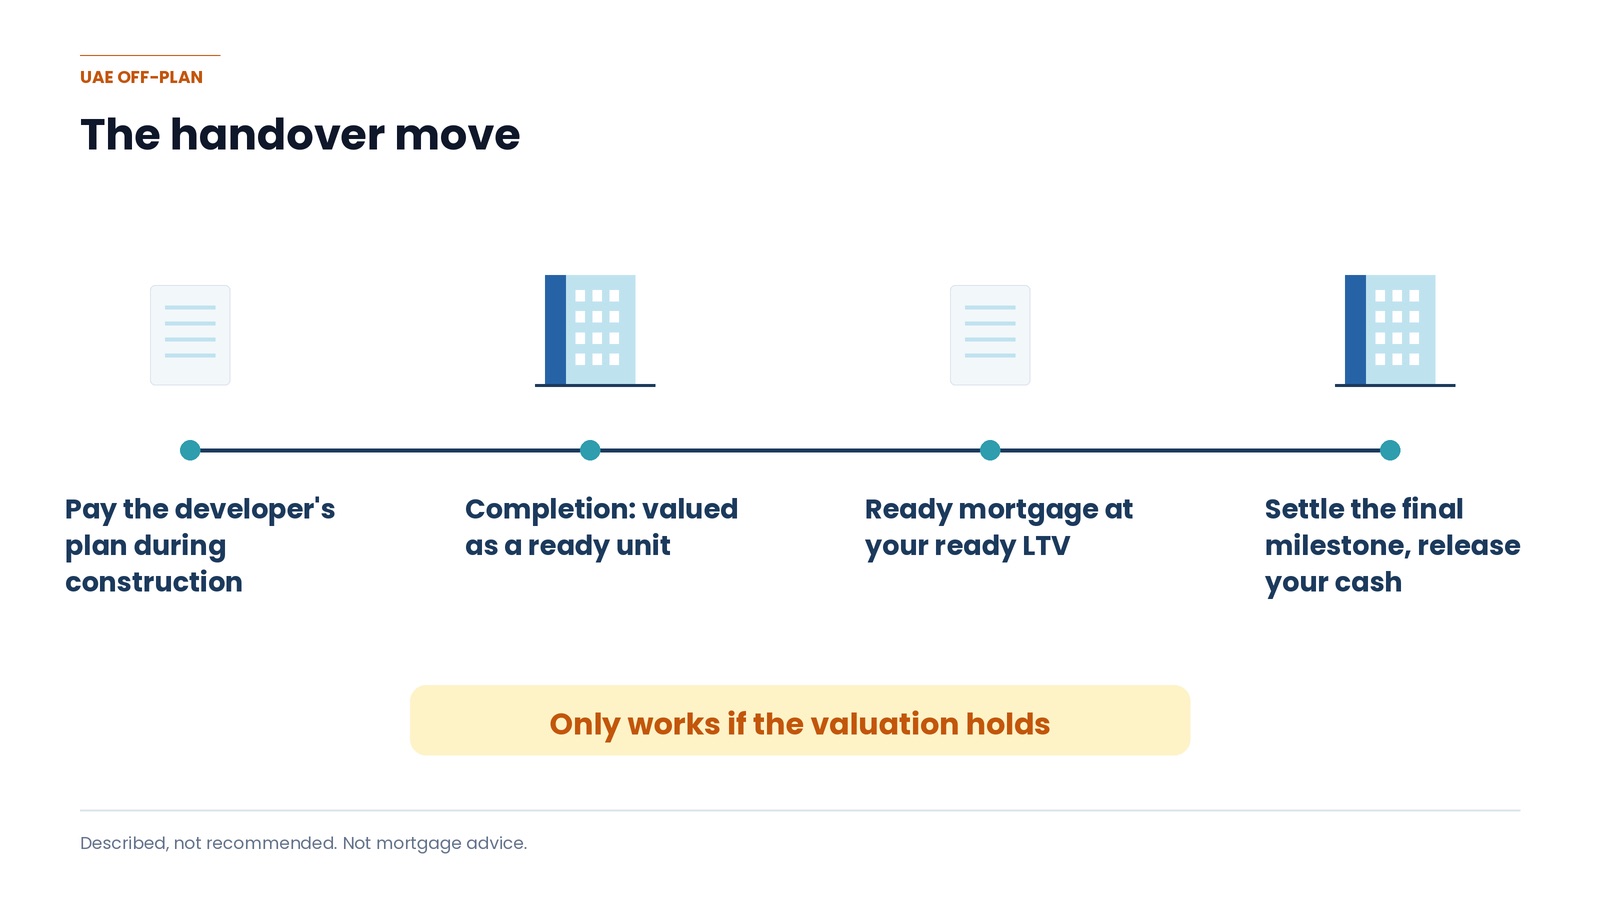
The handover move
There is a sequence that gets past the 50% ceiling. We are describing what the rules permit, not recommending it.
1. Buy off-plan and fund the construction phase through the developer's instalment plan.
2. On completion, the unit is valued as a ready asset.
3. Take a standard ready-property mortgage at that point, at your category's ready LTV rather than the 50% cap.
4. Use it to settle the developer's final milestone, releasing the cash contributed during construction.
⚠️ Three caveats the research does not supply, and they matter more than the sequence.
The valuation carries all of it. The sequence assumes the completed unit values at or above your contract price. A unit bought on a payment plan carrying a convenience premium is structurally more exposed to a shortfall.
The timing advice contradicts itself unless you read it carefully. Sources say arrange pre-approval 6 to 12 months before handover. They also say pre-approval is valid 60 to 90 days. Start the conversation early, take the formal approval late, expect to refresh it.
Handover slips, and the research does not say what happens to the sequence when it does.
What a bank will ask
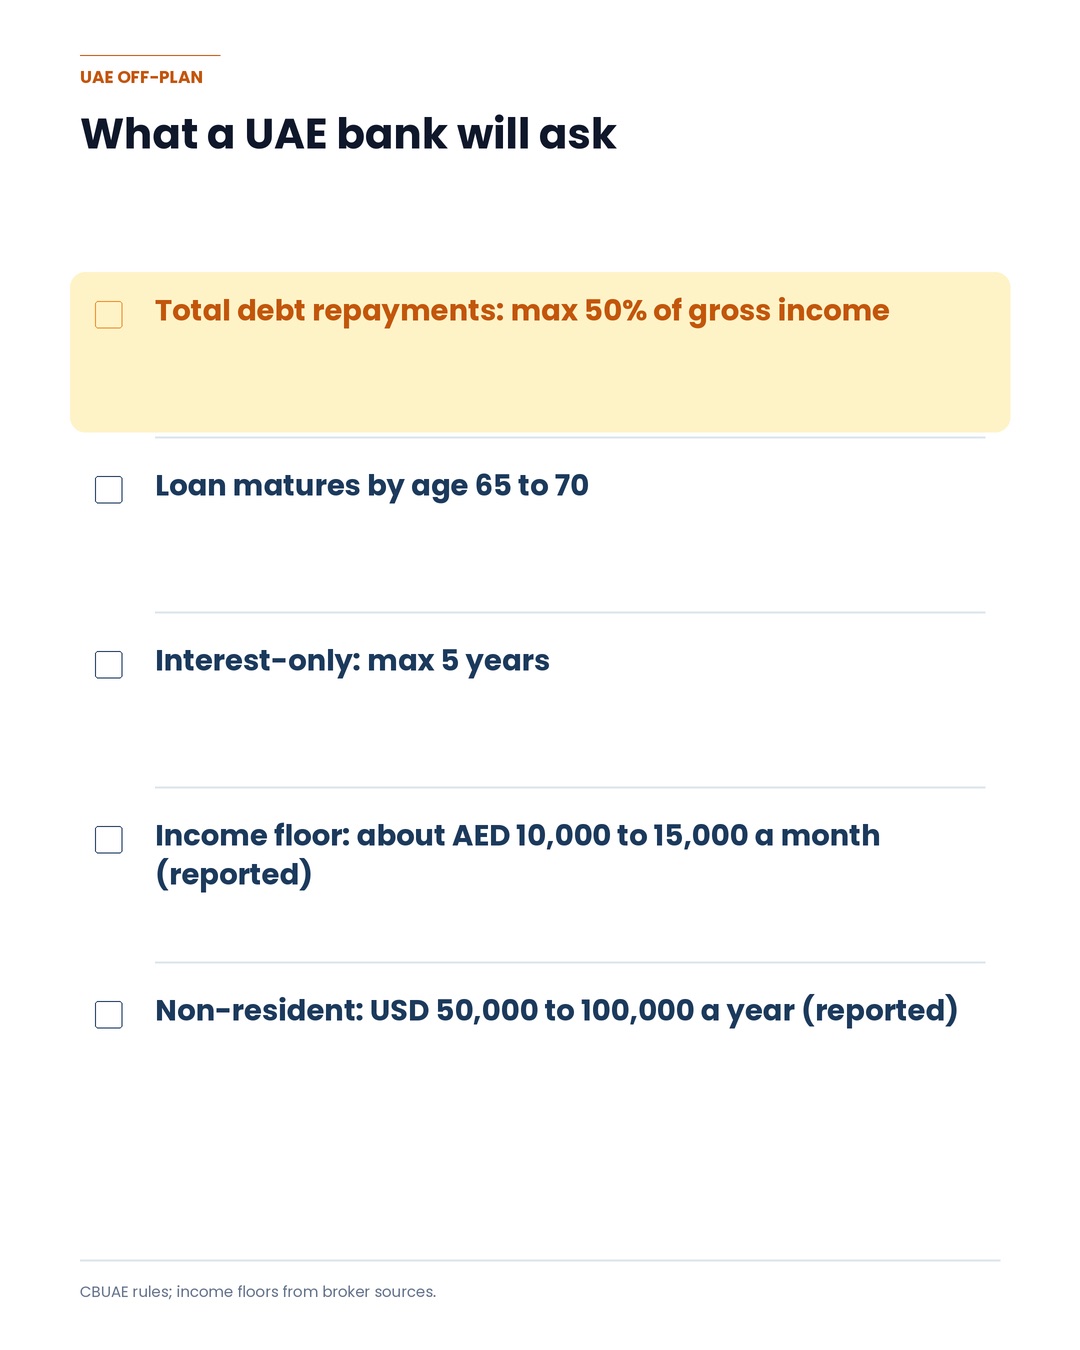
Debt Burden Ratio. Total monthly debt repayments including the new mortgage cannot exceed 50% of gross income. Car finance, cards and existing loans all count.
Age. Loans generally structured to mature between 65 and 70.
Interest-only. Capped at 5 years under the Central Bank regulations.
Income. Reported thresholds start around AED 10,000 to 15,000 monthly at some banks, with off-plan and handover products described as starting nearer AED 40,000. Broker-sourced, describing market shape rather than published criteria.
Non-residents. A reported minimum annual income floor of USD 50,000 to 100,000, and some banks' off-plan products are resident-only.
Pre-approval validity: 60 to 90 days.
The Abu Dhabi fee, settled
We have declined to publish an Abu Dhabi registration fee across several articles, because the figure appeared as 2%, 4% and 4.5% in different commercial guides.
It is 2%, and the source is TAMM, the Abu Dhabi government's own portal. ADREC's DARI documentation agrees.
| Charge | Amount | Source |
|---|---|---|
| Real estate registration fee | 2% | TAMM |
| E-service fee, sale and purchase registration | AED 875 | TAMM |
| Administration allowance, off-plan plot or unit | AED 450 | TAMM |
| Musataha fee, where applicable | 1% | TAMM |
| Late registration penalty, past 21 days | AED 10,000 | ADREC / DARI |
The AED 875 and AED 450 attach to different services and should not be added together.
Dubai is 4%. Abu Dhabi is 2%. If someone quotes you 4% on an Abu Dhabi transaction, ask where it comes from.
A correction we are publishing
An earlier article on this site stated that banks will not underwrite a mortgage on an off-plan property until physical completion.
That is wrong. Banks underwrite off-plan units at 50% LTV. The constraint is on disbursement, tied to construction progress.
We have corrected the original and we are noting it here rather than editing quietly, because a site that publishes its own corrections is worth more than one that does not.
[INLINE CTA #3]
We run the real cash requirement before any client makes an offer they intend to finance. Not because it is complicated, but because the difference between the LTV people model and the cash they need is about seven points of the purchase price, and finding that out after signing is the wrong time.
[Book a call]
FAQ
Can you get a mortgage on an off-plan property in Dubai?
Yes, capped at 50% of value by the Central Bank, and that cap applies equally to UAE nationals, resident expatriates and non-residents.
When does a bank release off-plan mortgage funds?
Typically once the project reaches 35% to 40% completion for residents, and around 60% for non-residents. Approval and disbursement are separate events.
Can I include DLD fees in my mortgage?
No. Since 1 February 2025 banks are prohibited from financing transaction fees.
How much cash do I need for an off-plan mortgage?
On an AED 2,000,000 unit at 50% LTV, approximately AED 1,132,000, or about 56.6% of the purchase price.
What LTV can a non-resident get?
50% on off-plan. On ready property our sources give 65% in one place and 75% in two others, so get it from a lender.
Can I refinance at handover to get a higher LTV?
The rules permit a standard ready-property mortgage once the unit is complete. It depends on the completed valuation supporting the loan. That is a description of what is permitted, not a recommendation, and it is a conversation for a mortgage adviser.
What is the property registration fee in Abu Dhabi?
2% per TAMM, plus a small e-service fee that differs by service and a 1% Musataha fee where applicable. Dubai's is 4%.
What is the maximum debt burden ratio?
Total monthly debt repayments including the new mortgage cannot exceed 50% of gross income.
Do you arrange mortgages?
No. We are brokers, not mortgage advisers. We will tell you what product you are eligible for and what cash it requires, so you stop modelling one you cannot have. The finance itself goes to a lender or a regulated adviser.
Final CTA block
Two paths.
If you want to understand the rules: download Fifty-Seven. 26 pages, a printable cash-requirement worksheet, no bank named and nothing recommended.
If you have a unit in front of you: send us the price and your buyer category and we will return your LTV ceiling and your real cash requirement with every fee itemised.
[Download the guide] [Run the numbers]
Disclaimer. This page is general information about mortgage rules applying to UAE off-plan property. It is not mortgage, financial or investment advice, and we are licensed real estate brokers rather than mortgage advisers. No bank, lender or product is named and none is recommended. LTV caps, fees and lending criteria change, and eligibility varies by lender. Confirm anything you intend to rely on with a lender or a regulated mortgage adviser before acting.